Intermodal Contract Rates Surge in Fourth Quarter Driven by Spiking Diesel Prices and Tightening Bid Cycles

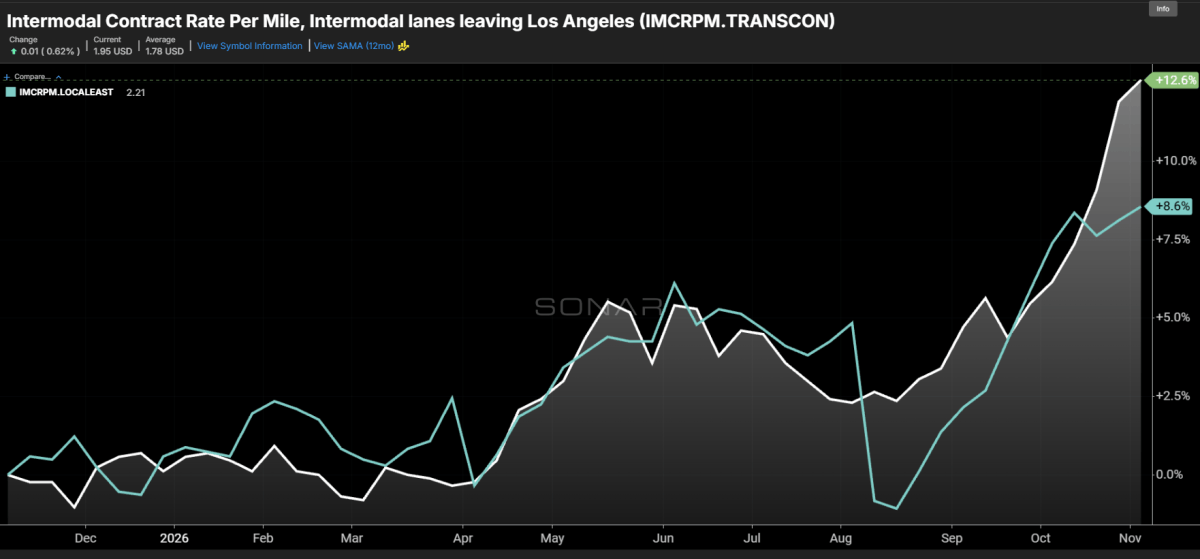
Intermodal contract rates inclusive of fuel have experienced a significant upward trajectory throughout the fourth quarter, reshaping the cost dynamics between rail and traditional trucking alternatives. According to recent data tracking transcontinental and regional Eastern lanes, transcontinental intermodal contract rates have climbed by more than 12% year over year. Simultaneously, shorter Eastern corridor lanes have registered increases approaching 9%. These movements highlight a broader recalibration of freight pricing models as carriers and shippers adjust to persistent macroeconomic volatility, fluctuating fuel expenses, and shifting capacity demands across North American supply chains.
Typically negotiated on annual cycles with the majority of agreements resetting near the conclusion of the calendar year, intermodal rates reflect both structural base rate changes and the immediate impact of volatile diesel markets. Because these indices are compiled using historical invoice data that generally lags actual freight movement by several weeks, price swings in diesel fuel manifest within the metrics with a distinct delay. This structural lag provides a clear explanation for the sharp upward adjustments observed over the trailing twelve months, mapping closely against sudden spikes in energy commodities earlier in the year.
The Chronology of Fuel Shocks and Rate Adjustments
The relationship between diesel pricing and intermodal rate indices became particularly pronounced during the spring and late summer months. A substantial escalation in diesel prices—amounting to an approximate 50% increase across March and April—was followed by a measurable 6% expansion in the transcontinental contract index between April and May. A secondary wave of energy market volatility materializing as a roughly 36% rise in diesel costs from July to September triggered a subsequent 10% jump in the transcontinental index from August to October.
This statistical alignment indicates that fuel dynamics are responsible for a dominant share of the observed rate increases. Analytical breakdowns suggest that fuel surcharges account for roughly two-thirds of the total transcontinental rate rise and roughly three-quarters of the increase observed on Eastern lanes. Standard published intermodal fuel surcharge schedules, if applied uniformly, would theoretically imply a fuel-driven impact exceeding the entirety of the recorded index increases. However, the more modest actual increase points to a widespread industry practice wherein major shippers negotiate customized, less aggressive surcharge tables with their rail and intermodal marketing company partners. This structural nuance remains critical during negotiations, as service providers and procurement teams ultimately evaluate the total landed rate rather than isolated components.
Corporate Reactions and the Bid Season Landscape
Major logistics enterprises have reported contracting environments that mirror these data trends. Major intermodal operators, including J.B. Hunt, indicated securing only low-single-digit base rate increases during the annual bid season that officially concluded in September. This restrained base rate growth aligns with indices capturing the inception of these fresh contracts. Analysts suggest that elevated baseline fuel surcharges effectively capped base rate expansion, as total pricing was already elevated by prevailing energy costs, leaving less room for carriers to demand aggressive increases on the underlying transportation service.
This dynamic creates a persistent structural dilemma for both shippers and carriers operating in volatile commodity environments. High fuel surcharge allocations introduce greater price volatility into logistics budgets. Conversely, locking in contracts when energy prices are elevated exposes total expenditure to downward adjustments over the contract lifespan if fuel markets soften. Conversely, when fuel constitutes a smaller fraction of the overall rate, operational costs maintain greater consistency throughout the year, though shippers forfeit the immediate cost-relief benefits typically associated with falling fuel markets. Industry consensus maintains that fuel surcharges are designed as risk-sharing mechanisms to absorb commodity price fluctuations rather than functional profit centers for transportation providers.
Intermodal Cost Competitiveness and Truckload Parity
Despite the cumulative rate increases recorded through the fourth quarter, intermodal transportation retains a substantial pricing advantage over traditional dry van truckload services. The Intermodal Contract Savings Index, which systematically measures average rate differentials between comparable truckload and intermodal lanes across North America, continues to demonstrate an average savings profile of approximately 30% for intermodal shippers. While this metric has retreated modestly from its annual peak of 33% registered in June, the remaining margin underscores the enduring economic viability of rail-truck hybrid logistics.
Industry analysts anticipate that the full impact of fourth-quarter rate resets will become completely transparent within logistics data feeds in the coming weeks. Even with these adjustments, intermodal is projected to preserve its position as a primary cost-mitigation alternative for high-volume shippers. Nevertheless, structural vulnerabilities within the rail network continue to influence operational planning. Recent disruptions, including severe weather-related infrastructure washouts affecting BNSF lines in New Mexico alongside technological outages experienced by CSX, serve as acute reminders that rail networks remain susceptible to localized bottlenecks and physical disruptions comparable to traditional highway networks.
Despite these operational hurdles, cargo owners have demonstrated resilience, absorbing short-term disruptions with minimal long-term diversion to the highway. Intermodal volumes have rebounded steadily across major corridors, maintaining an annualized growth trajectory of approximately 7%. As the logistics sector prepares for the upcoming calendar year, the interplay between fuel price volatility, infrastructure resilience, and underlying rail economics will continue to dictate pricing strategies across transcontinental and regional shipping lanes.
Related posts: